Europe's Sovereign-Grade AI Cloud.
Eumera AI delivers the AI capabilities of the world's largest technology companies to Europe's most regulated organisations; without compromising on security, privacy, or control. Sovereignty by corporate structure, not by marketing.
Sovereign AI compute at hyperscale
NVIDIA training clusters and AMD inference fleets across four EU sites featuring air-gapped tenancy, SecNumCloud 3.2 alignment and a 12-month chip-to-revenue delivery cycle your hyperscaler cannot match.
Solutions for regulated buyersThe second wave of neocloud value
A €22.9B capital programme building 500 MW of EU-controlled AI infrastructure by FY2030; targeting the €18B regulated-buyer market that hyperscalers structurally cannot serve.
Investment overviewThree structural advantages competitors cannot replicate
Not because of technology; because of structure. Each advantage compounds into a defensible moat for the European regulated-buyer market.
EU sovereignty by structure
French SAS operator under a Luxembourg Master SOPARFI with EU-control covenants from incorporation. Built to clear the SecNumCloud 3.2 look-through test by design; not retroactively applied. US-parented hyperscalers and UK-origin neoclouds structurally cannot pass it.
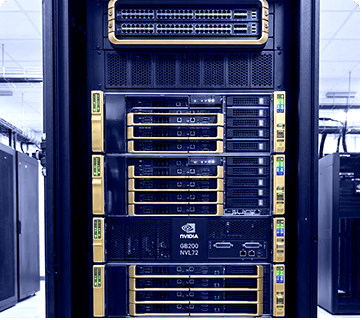
Delivery certainty
A Developer and EPC partnership master design-build agreement covers all four sites under guaranteed maximum price, liquidated damages, and performance bonds. 12 months from GPU order to first paid GPU-hour, roughly twice as fast as the 30–42 month industry benchmark.
Silicon flexibility
NVIDIA GPUs for training, AMD GPUs for inference, from FY3. An OpenXLA portability layer lets customers migrate workloads across all three silicon lines, providing optionality against vendor concentration risk.
€18B of regulated demand. No compliant supply at scale.
The EU regulatory stack, AI Act, DORA, NIS2, EHDS, SecNumCloud 3.2 reached implementation maturity in 2026. Regulated buyers can no longer defer sovereign compute decisions yet, over 35% of enterprise AI spend remains blocked by compliance concerns.
Regulated-buyer AI compute market: financial services, defence, healthcare, telecoms, public sector.
As sovereignty programmes mature and enforcement tightens across the EU27.
Of enterprise AI spend currently blocked by compliance will migrate to compliant alternatives, not hyperscalers.
Global neocloud market by 2031 (Synergy Research, 58% CAGR from $20–35B in 2026).
Four sovereign sites. One reference architecture.
Delivered under a single master agreement, selected for renewable power, buyer proximity, national certification, and physical security for sovereign-defence tenancy.
- GPUs
- ~24k
- Power
- Power Grid
- Status
- RFS Q3 2027
- GPUs
- ~19.3k
- Power
- Hydro
- Status
- Ready Q3 2027
- GPUs
- ~14.5k
- Power
- EnBW green tariff
- Status
- RFS Q4 2027
- GPUs
- ~76k
- Power
- BTM Power Grid
- Status
- Operational Q2 2028